Pump.fun copy traders risk buying the hype
Pump.fun copy traders risk following wallets whose multimillion-dollar gains come from transactions they cannot replicate, new blockchain research shows.
An Oct. 22 investigation by Bitquery found that only 26% of $752.5 million in large memecoin wallet gains passed its checks for conventional market trading, raising questions about the profitability rankings investors use to identify successful traders.
The study examined 3,170 wallet-token positions with reported gains of at least $100,000 between October 2025 and August 2026. It found that 51% of the gains involved wallets selling tokens received from other addresses, while another 13% exhibited patterns of potentially coordinated trading. The remaining 10% could not be conclusively classified.
The findings expose a weakness in crypto copy trading, where investors use automated platforms to mirror transactions made by wallets with strong historical returns.
These systems typically rely on observable purchases to establish positions. However, wallets receiving tokens through transfers can record substantial profits without executing a market purchase that followers could replicate.
The practice also appears to be growing. Bitquery found that transferred-token sales accounted for seven out of every 10 large wallet wins in August, after remaining below 100 cases monthly until July.
The shift suggests that traders increasingly relying on wallet leaderboards could encounter apparently profitable addresses whose trading histories provide little indication of the returns available to outside investors.
Why profitable wallets may offer no trades to copy
Bitquery identified 1,579 profitable positions where most of the tokens sold had arrived through transfers rather than purchases recorded by the selling wallet.
Of those, 1,104 could be traced to addresses associated with the token’s creator, either directly or through intermediary wallets.
This arrangement can distort address-level profit calculations because tracking platforms typically subtract recorded purchases from sales to determine profitability.
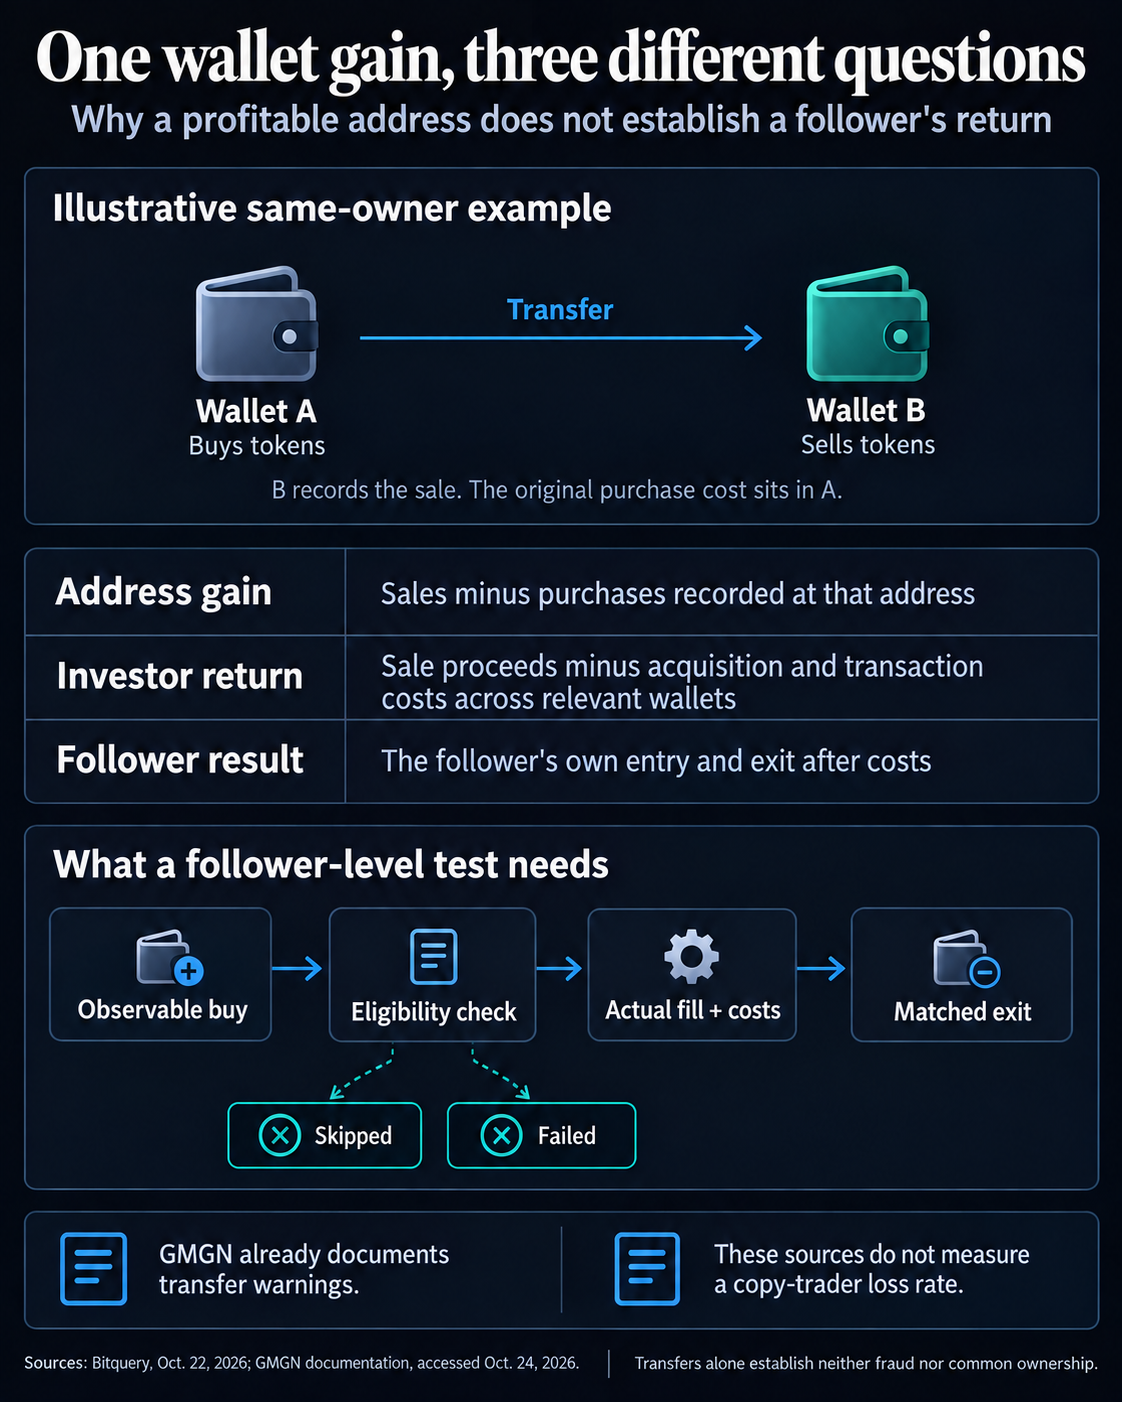
An investor might purchase tokens through one wallet, transfer them to another and subsequently sell them after a substantial price increase.
The receiving address could then display significant profits despite recording no acquisition cost. However, the investor’s actual return would still depend on what the original wallet paid.
A copy trader monitoring the receiving address would see the eventual sale without receiving the purchase signal needed to enter the position at a comparable price.
Bitquery also identified 423 creator-linked transfers involving additional signing addresses. In one example involving the UOTF token, four temporary wallets received nearly eight million tokens each before forwarding them to selling addresses in a coordinated transaction.
One recipient subsequently sold its holdings for $1.59 million, producing a large apparent gain without a corresponding recorded market purchase.
Such transactions can make concentrated token distributions resemble successful trading activity across several independent wallets.
However, transfers can also occur between wallets belonging to the same legitimate investor. The absence of a recorded purchase therefore does not independently establish manipulation.
Bitquery found another complication among the biggest winners. Fifteen of the 25 largest reported gains met its criteria for wash loops, where concentrated buying activity coincided with direct financial links between wallets.
One example involved Arena, where a wallet spent $4,223 before recording approximately $4.92 million in sales.
Another address, previously funded by the apparent winner, accounted for 99% of buying activity during the holding period. Bitquery said the seller had transferred more than $1.4 million in SOL to that buyer over the preceding two days.
The pattern raises questions about whether an outsider could reproduce the returns without access to the same buying support.
Copy-trading platforms face a profitability test
The findings put greater scrutiny on the wallet analytics used by platforms such as GMGN, which allows investors to monitor addresses and automatically replicate their trades.
GMGN’s documentation already includes warnings labeled “Didn’t buy” and “Sold > Bought,” identifying addresses that receive tokens without purchasing them or sell more than their recorded acquisitions.
However, those indicators do not establish whether the gains displayed in a wallet’s trading history could have been achieved by its followers.
GMGN’s copy-trading system executes purchases based on buying transactions made by monitored wallets. Its proportional selling feature applies only to tokens acquired through the copy-trading service.
Consequently, a wallet receiving tokens through transfers provides no corresponding market purchase for the automated follower to mirror.
Even conventional purchases introduce additional obstacles. GMGN allows users to configure liquidity, market capitalization and transaction-size filters that can prevent orders from being copied.
The platform also charges a 1% handling fee per transaction, excluding network and priority costs. Slippage and execution delays can further reduce returns, particularly when investors follow wallets trading rapidly.
Bitquery identified genuine profitable activity in its sample, including a SOULGUY position that generated $3.3 million across 3,632 trades. Replicating such performance would require followers to execute frequent transactions at sufficiently competitive prices.
GMGN provides records of successful and failed copied orders, offering a basis for comparing wallet activity with actual execution. Its published documentation, however, does not establish whether profitability rankings account for transferred inventory or the returns available to followers.
The gap remains unmeasured. Bitquery did not examine copy traders’ actual performance, while another 2,943 six-figure winning positions closed after its August cutoff and remain outside the study’s transfer analysis.
Assessing those newer positions, alongside completed and missed copy-trading orders, would help establish how much of the apparent profitability displayed on wallet leaderboards translates into executable trading opportunities.
Originally published by cryptoslate.com →